
Financial Strategy · Collection operations · Control guide
How to Create a Better Fee Collection Process in a Study Library
Build a member-friendly, auditable workflow from a valid obligation to verified payment, allocation, receipt, outstanding balance, closing and reconciliation.
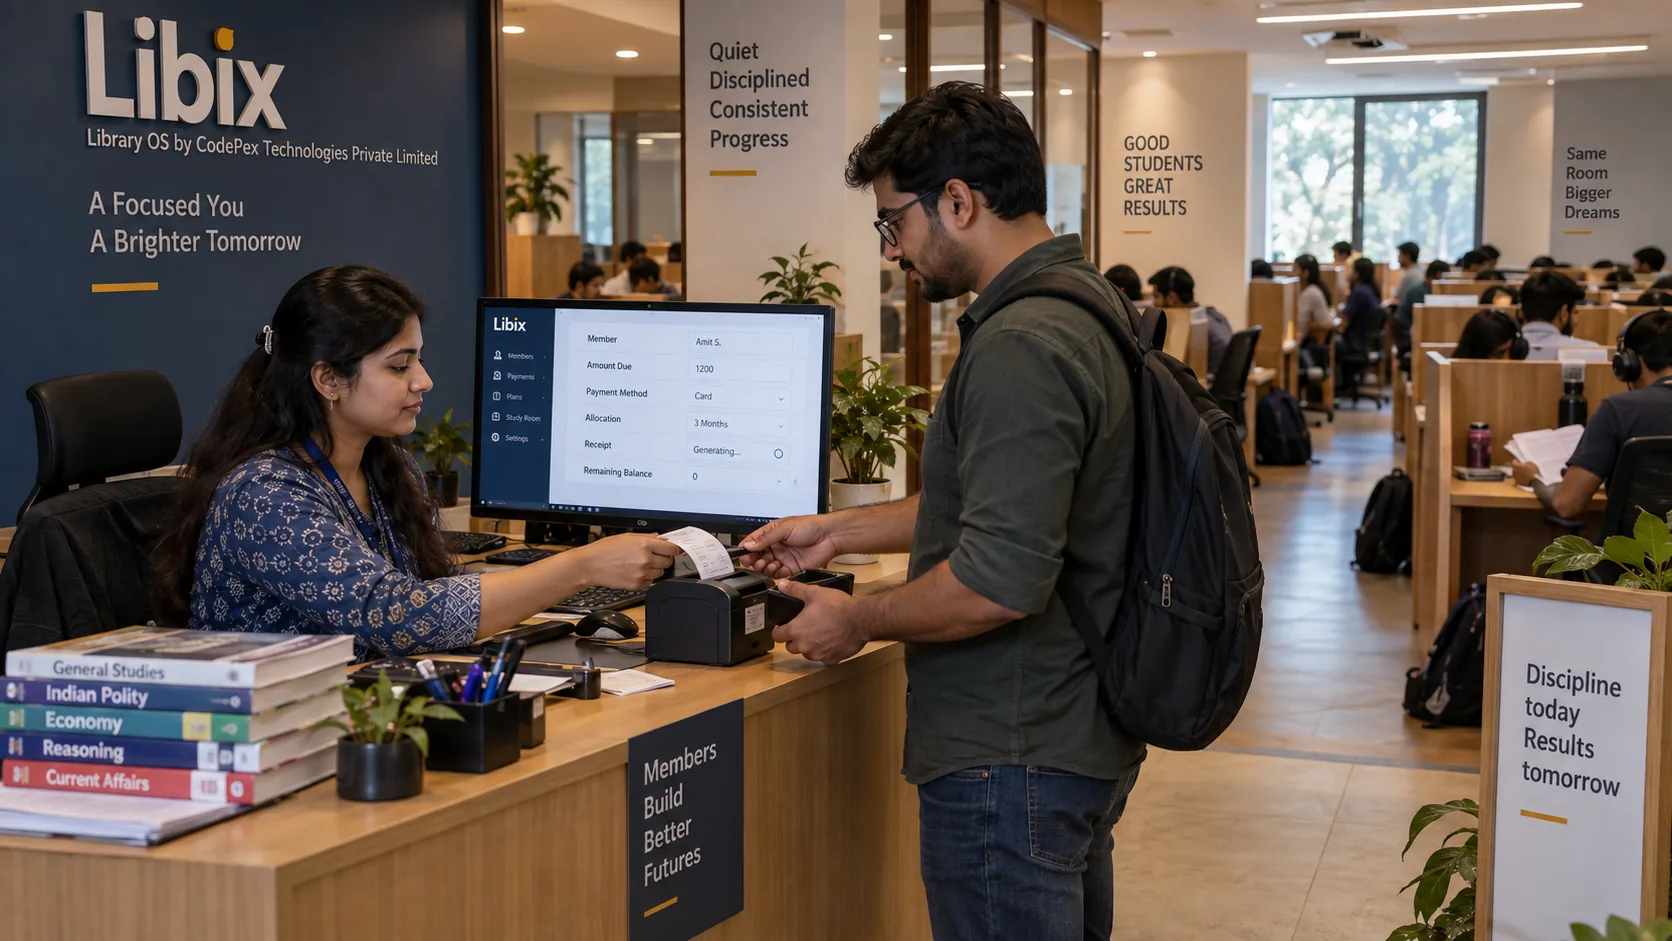
Quick answer: collection starts before payment
A better process first establishes a valid amount due. It then makes that amount clear, prepares staff, accepts and verifies the payment, records it once, allocates it to the correct obligation, issues a truthful receipt, updates outstanding, routes exceptions, closes the period and reconciles records with actual money movement.
Price ≠ Charge/Invoice ≠ Payment ≠ Allocation ≠ Receipt ≠ Outstanding. Payment method is not payment status, and a screenshot is not authoritative confirmation.
1. Define the obligation
Collection should begin with a valid charge or invoice. Establish the member, membership period, purpose, base amount, approved concession or credit, adjustments, amount due, due context and relevant branch or document information before asking for payment.
A plan price is not automatically the current payable amount. Previous payments, credits, authorized discounts and adjustments can change what the member owes. Front-desk staff should not invent or silently edit the amount at collection time.
Make due clear
Show the purpose, period, amount, adjustments, previous settlement, outstanding and due context.
Avoid ambiguity
A vague “fees pending” message creates disputes. Communicate the exact valid amount and what it relates to.
Amount-due builder
Start with a valid obligation
This model keeps the financial chain visible: obligation → payment → allocation → receipt → outstanding. It is educational, not a live payment system.
The illustrative payment is fully allocated. Preserve the original obligation and derive the remaining balance.
Verification state
Payment method is not payment status
Illustrative state: UPI / electronic · Successful
A screenshot is not authoritative confirmation. Verify through actual cash counting or the appropriate provider/bank/integration state.
End-of-period control
Closing and reconciliation are different questions
Closing asks
What does the internal collection system say happened at this counter, branch or period?
Reconciliation asks
Does that record agree with independent physical cash, bank or provider evidence?
Record once, then allocate deliberately
A payment needs a unique identity, amount, method, status, member, timestamp, branch or counter context, collector and external reference where relevant. Retries and repeated callbacks must not create duplicate payments.
Allocation explains what the payment settles. A ₹2,000 payment might allocate ₹1,500 to one charge and ₹500 to another. The payment remains one payment; the allocation records its use.
Partial payments preserve the original obligation. Overpayments must be handled explicitly as an advance, another valid allocation, credit or refund according to policy. They should not silently become revenue.
Verify according to the payment method
Cash requires actual receipt, counting and controlled closing. Electronic payments require the appropriate provider, bank or integration state. A QR scan, transfer screenshot or member assertion is not itself authoritative proof of successful settlement.
| State | What it means | Collection treatment |
|---|---|---|
| Pending | Attempt or provider state is unresolved | Do not count as successful collection or issue a successful receipt |
| Successful | Authoritative verification is complete | Record, allocate and document according to the valid obligation |
| Failed | Payment did not settle | Retain useful attempt history and permit controlled retry |
| Reversed | Earlier settlement was unwound | Use linked reversal workflow; do not delete the original event |
Issue truthful receipts and derive outstanding
A receipt should reflect the recorded successful transaction, member, amount, method, date/time, reference and allocation context. A pending or failed payment should not produce a successful-payment receipt.
Outstanding should be derived from valid obligations, valid allocations and applicable credits or adjustments. Avoid manually typing balances that can drift from the underlying financial story.
Receipt
What was recorded as received?
Outstanding
What remains from valid obligations?
History
Can another authorized person explain the movement?
Design the exception path
Real collection operations include partial payments, overpayments, pending or failed transactions, duplicate attempts, wrong allocations, informal discount requests, refunds, reversals, credits and backdated corrections. Route each exception to an explicit workflow rather than editing the original event until the numbers look convenient.
Refunds and reversals should link to the original transaction. Corrections should preserve the audit trail. Backdating needs permission, reason, evidence and impact review because it can change dues aging, closing and reporting.
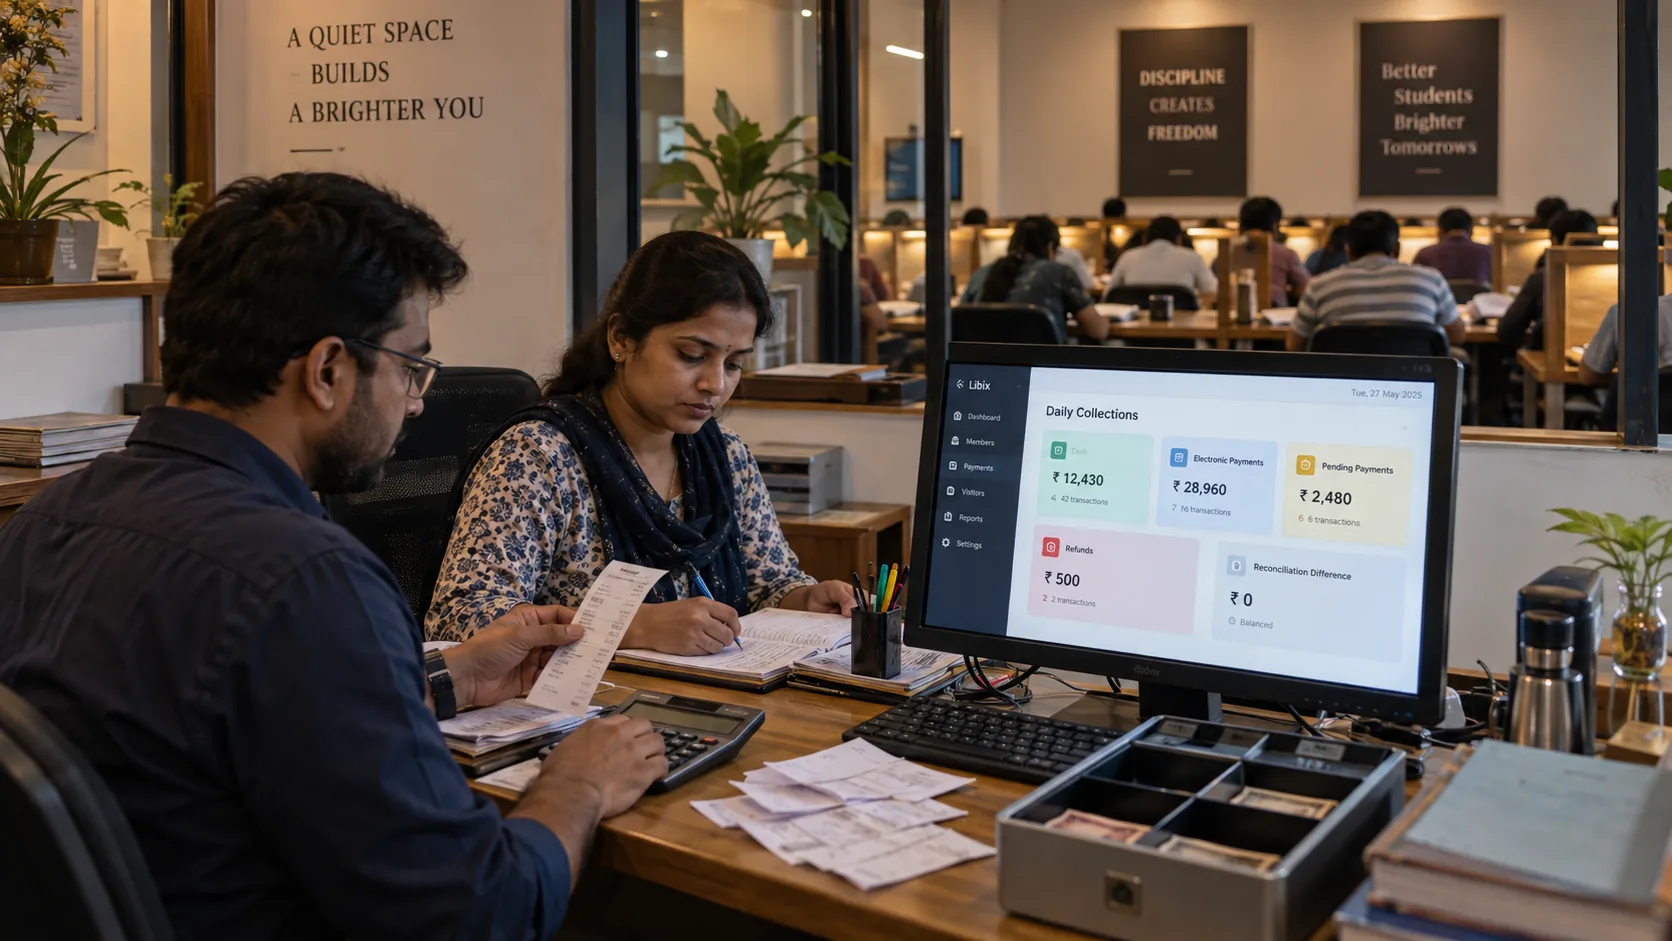
Close the period, then reconcile independently
Daily cash closing asks what the internal system expects at a counter or branch. Compare expected cash with physical cash, document discrepancies and investigate them without editing source transactions merely to make the drawer match.
Electronic reconciliation compares system payment records with provider or bank evidence. Account for successful, pending, failed, reversed and refunded states plus settlement timing where relevant. Closing is not reconciliation.
Cash difference
Physical cash − expected system cash. Record and investigate the difference.
External reconciliation
System payment records ↔ bank/provider records under defined filters and states.
Use permissions and context as controls
Preserve branch, counter, collector, account, allocation target and settlement context. Bank or payment account does not automatically equal operational branch. Use least privilege for viewing dues, collecting, recording manual payments, verifying, allocating, refunding, backdating, closing, reconciling and exporting.
For multiple branches, preserve the collecting branch and the obligation or allocation context. A centralized receipt of money should not erase where the operational event occurred.
Review collections at a useful cadence
Daily
Successful collections, pending/failed, unallocated money, refunds, cash differences and material exceptions.
Weekly
Dues movement, repeated failures, branch patterns, unresolved reconciliation and process errors.
Monthly
Collections alongside billing, outstanding, renewals, discounts, refunds, cash flow, budget and branch performance.
There is no universal ideal collection rate. If using one, state the population, period, numerator, denominator and treatment of refunds, credits and advance collections.
Where Libix fits
Libix — Library OS, from CodePex Technologies Private Limited
Libix is positioned for connected study-library operations around memberships, charges, payments, allocations, receipts, dues, refunds, branches, roles and reports. Current support for any particular payment provider, callback, automation, numbering or reconciliation workflow must be verified against approved product documentation and the live implementation.
Fee collection SOP
Frequently asked questions
What is the first step in a good fee collection process?
Confirm the valid obligation before accepting money. The member, membership period, amount, adjustments, due context and branch should be understandable.
Is a plan price the same as the amount due?
Not necessarily. Discounts, credits, prior payments, adjustments and outstanding balances can change the current payable amount.
Is a payment screenshot proof that payment succeeded?
No. Verify through actual cash controls or the appropriate provider, bank or integration state before treating the payment as successful.
Should a partial payment reduce the original charge?
No. Preserve the original obligation, record the payment and allocation, then derive the remaining outstanding amount.
What is the difference between closing and reconciliation?
Closing summarizes internal collection records. Reconciliation compares those records with independent cash, bank or provider evidence.
Is collection the same as revenue?
No. Revenue, collection, cash and profit are different concepts and should not be collapsed into one status or report.