
Start with definitions and assumptions
Decide what the budget measures: expected memberships, realized price, revenue, collections, operating expenses, owner compensation, financing, capital expenditure, tax or other items relevant to the business. Keep the source, period, population and assumptions visible so actuals can be compared consistently.
Budget revenue and collections separately
Expected revenue may be based on paid memberships, plan mix and realized price. Expected collections depend on payment timing, outstanding balances, partial payments, renewals, advances and collection policy. A high billed amount does not automatically produce the same cash in the month.
Budget fixed, variable and irregular costs
Rent and some staff or software costs may behave as fixed within a relevant range. Electricity, payment charges, cleaning or consumables may vary. Maintenance, annual renewals and repairs need timing assumptions. Step costs may appear when a new shift, branch or staffing level is added. Do not hide irregular costs because they do not occur every month.
Build the cash bridge
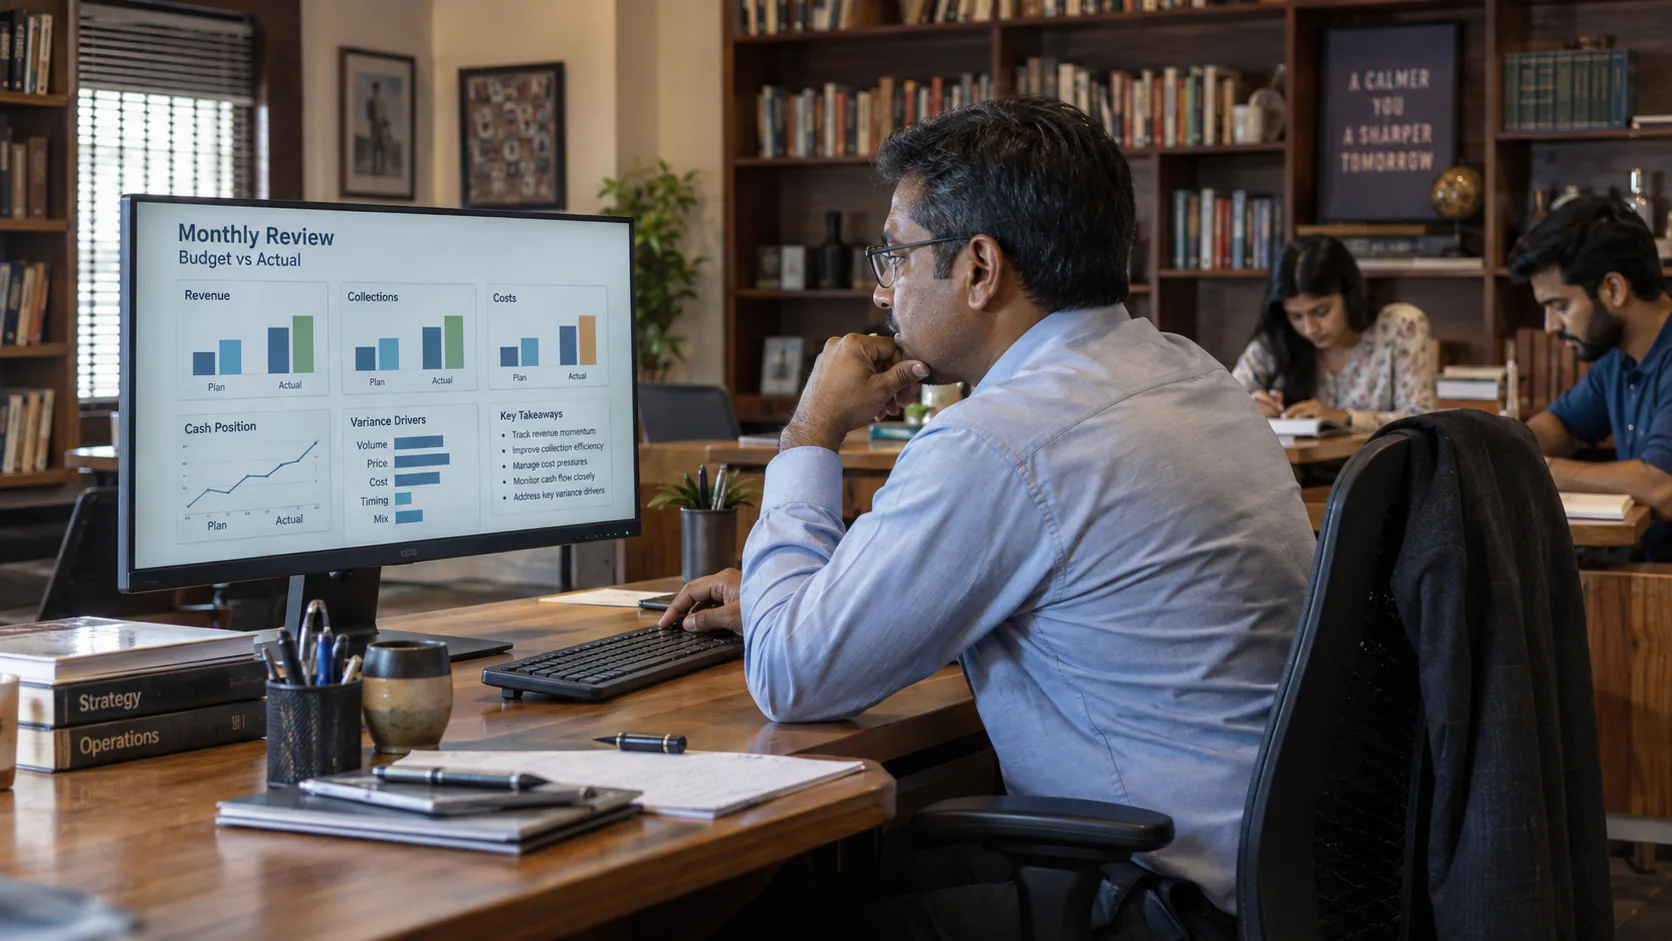
A cash view should connect opening cash, expected receipts, operating payments, financing payments, capital expenditure, owner withdrawals where relevant and closing cash. Cash planning helps identify timing pressure; it does not replace profit analysis or applicable accounting treatment.
Review Budget-vs-Actual variance
Variance is actual minus budget under consistent definitions. Investigate whether a difference came from volume, price, timing, collection, cost, scope, one-off events, seasonality or an incorrect assumption. An underspend may represent efficiency or a missed service expense. Revenue above budget may create capacity or service-quality pressure.
Use a rolling forecast without destroying history
Keep the original approved budget, actual source records, variance explanation and updated forecast distinguishable. A forecast can learn from evidence about the remaining months. It should not rewrite the original plan to make performance appear accurate after the fact.