
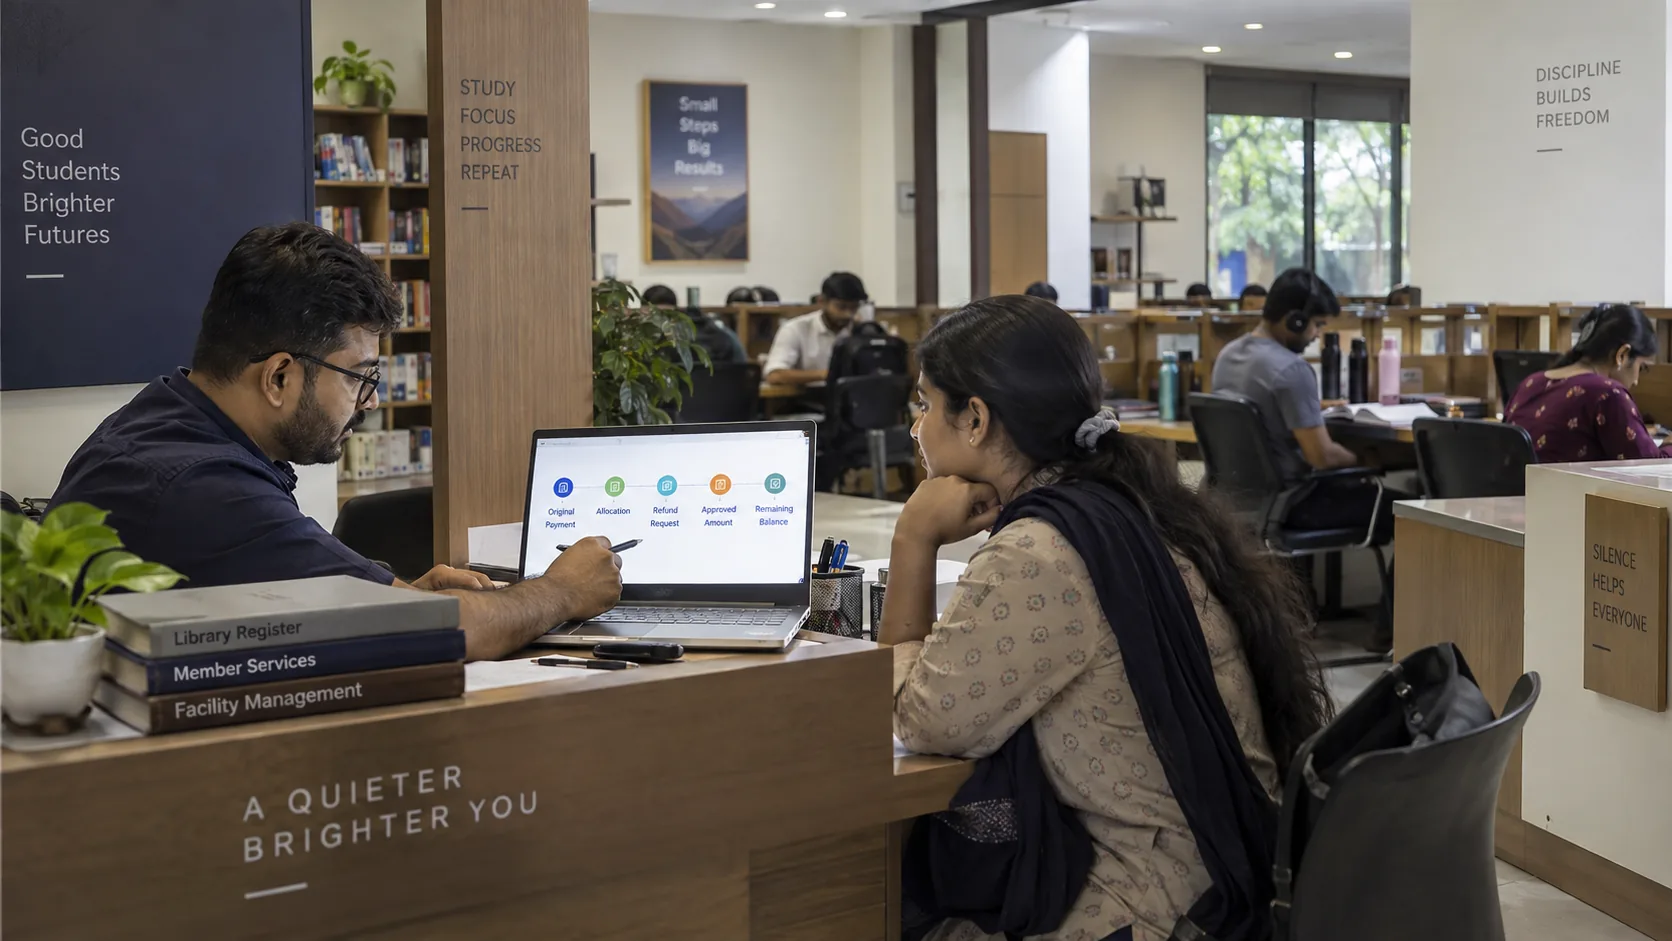
Define the financial event correctly
A refund represents eligible money returned or formally processed for return. A payment reversal unwinds the settlement effect of an earlier payment when that event should no longer count as valid settlement. An allocation reversal corrects how a valid payment was assigned without necessarily returning money. A charge or invoice adjustment changes the obligation itself. These events may produce similar final numbers while describing different economic facts.
Why deleting the original payment is wrong
If a member paid ₹1,500 and ₹500 was later refunded, the truthful history is ₹1,500 received followed by ₹500 returned. Editing the original payment to ₹1,000 falsely claims that only ₹1,000 was ever received. Preserve the original receipt and add a linked refund or reversal document. This protects collection reports, member questions, cash or bank reconciliation and later review.
Start with the authoritative transaction
Before processing, identify the member, source payment, amount, method, date, provider reference, status, allocations, related charge, prior refunds, prior reversals, outstanding amount and membership context. A refund amount must be derived from the valid financial context, not from memory or a client-calculated number. Use decimal-safe money arithmetic and apply the configured currency and rounding rules.
Full, partial and multiple refunds
A full refund returns the valid refundable amount under the policy. A partial refund returns only an approved portion. Multiple refunds against one payment require cumulative validation: successful refunds must not exceed the valid refundable amount. Pending or failed attempts must not be counted as successfully returned money, and a retry must be idempotent so one request cannot create duplicate successful refunds.
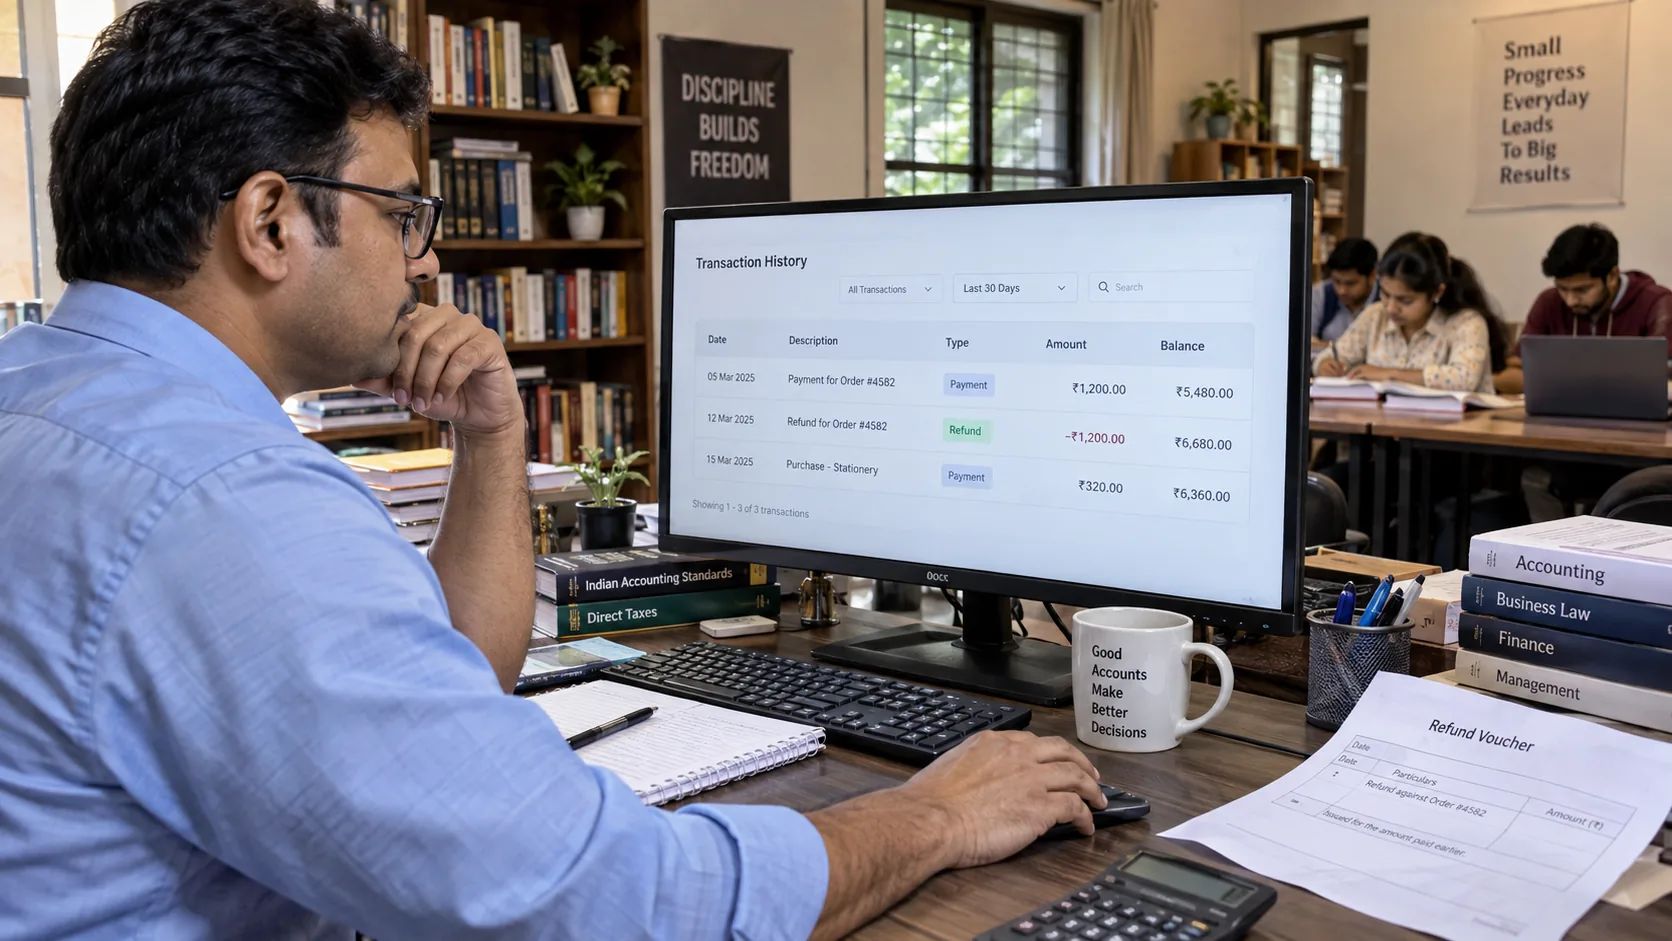
Allocations, overpayments and duplicates
When one payment settled multiple charges, a refund or allocation reversal can affect several balances. Show the original allocations, proposed event, restored outstanding amount and remaining valid allocation. For an overpayment, explicitly choose between retaining a permitted advance, allocating it to a valid obligation or returning it. If one real collection was duplicated in software, preserve the source events and use an authorized correction path; do not create a fictional second collection or silently classify it as revenue.
Cancellation and lifecycle events do not decide refunds automatically
Membership cancellation, freeze, extension or plan change may trigger a financial evaluation, but none automatically determines refund entitlement. Keep the membership decision and financial decision separate. Credits, discounts and obligation adjustments are also distinct from refunds because they change the amount owed rather than necessarily moving money.
Cash, electronic and gateway evidence
Cash refunds need authorization, cash-counter evidence, acknowledgement and cash-closing impact. Electronic refunds need a provider reference, provider status and bank or settlement evidence. A gateway or provider reversal can be different from a merchant-initiated business refund. Verify the provider status instead of trusting a client redirect or screenshot. Tax, credit-note and accounting treatment must be verified for the applicable situation.
Backdating, permissions and reconciliation
Backdated events deserve stronger permission, reason and impact checks because they can change collections, outstanding balances, cash closing, accounting periods and reports already relied upon. A controlled workflow may separate request, review, approval, execution, status updates and reconciliation. Reports should separate refund and reversal totals instead of combining them into one unexplained negative-collections figure.