
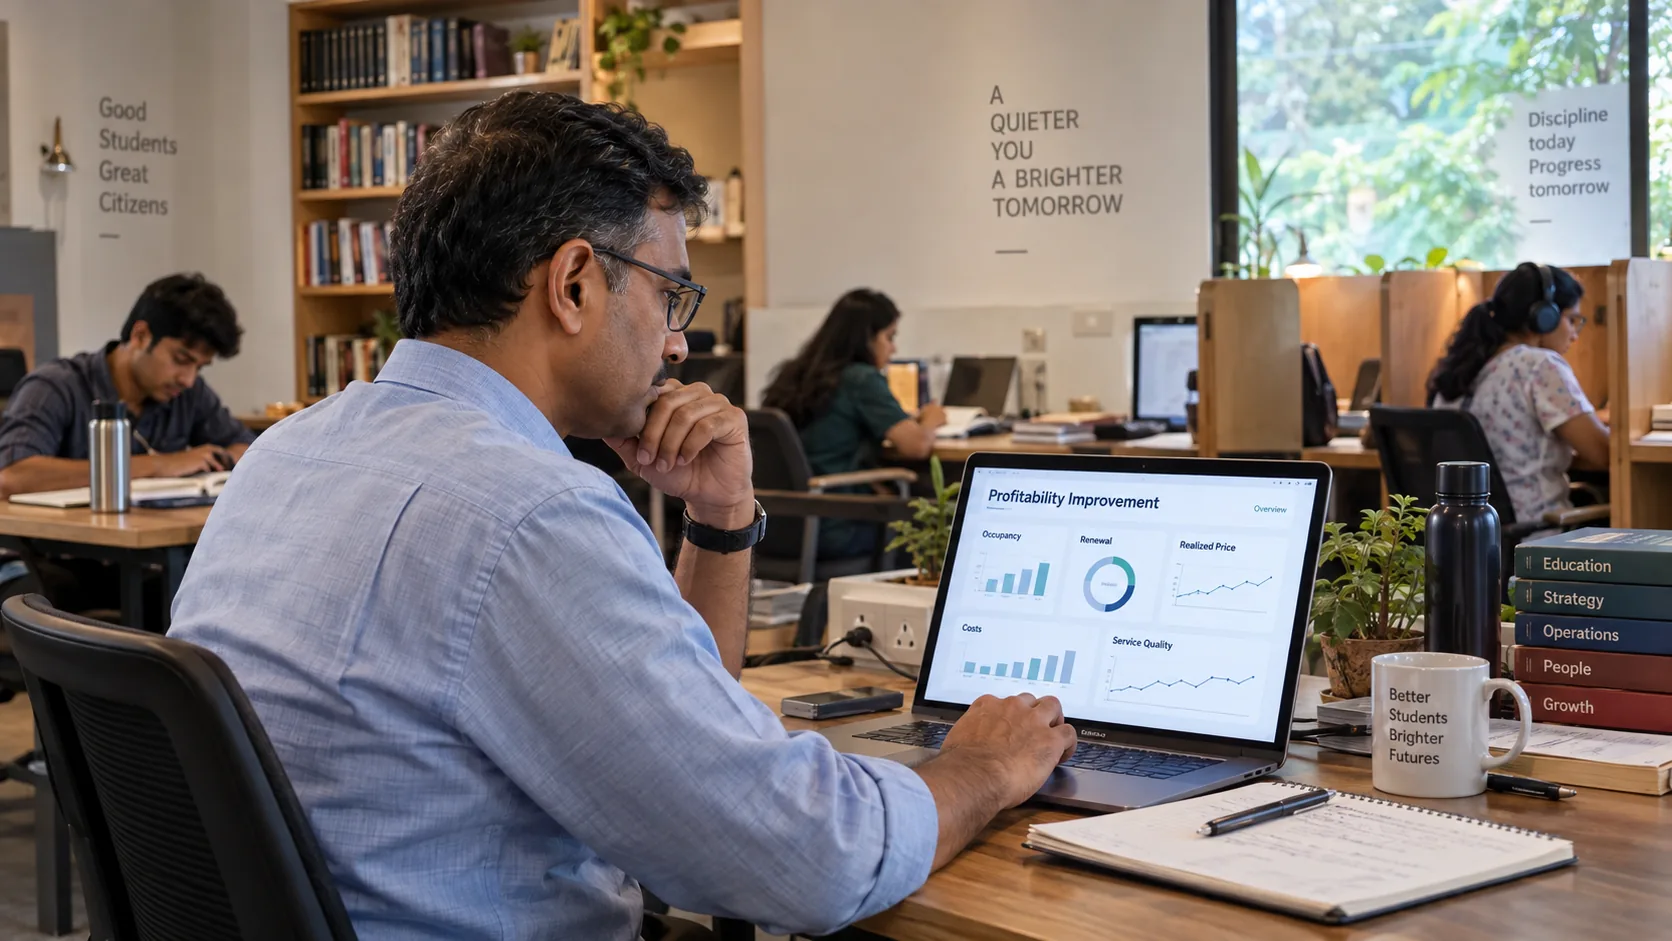
Diagnose before acting
Weak profitability can come from low paid utilization, weak realized price, poor renewals, outstanding collections, cost behaviour, productivity, leakage, service quality or an operating model that is too complex. A price increase, cost cut, extra shift or promotion can improve one measure while damaging another.
Revenue and utilization levers
Use capacity more effectively only when the service can support it. Review paid utilization, shift mix, plan mix, seat quality, legitimate add-ons and realized price. Empty seats may represent demand, timing, service, location or pricing problems; do not assume one cause from one metric.
Renewals and collections
Renewals can improve continuity and reduce repeated acquisition work, but the quality of the relationship matters. Collections affect cash and outstanding balances, but collected money is not automatically revenue or profit. Preserve partial payments, refunds, reversals and dues as distinct financial facts.
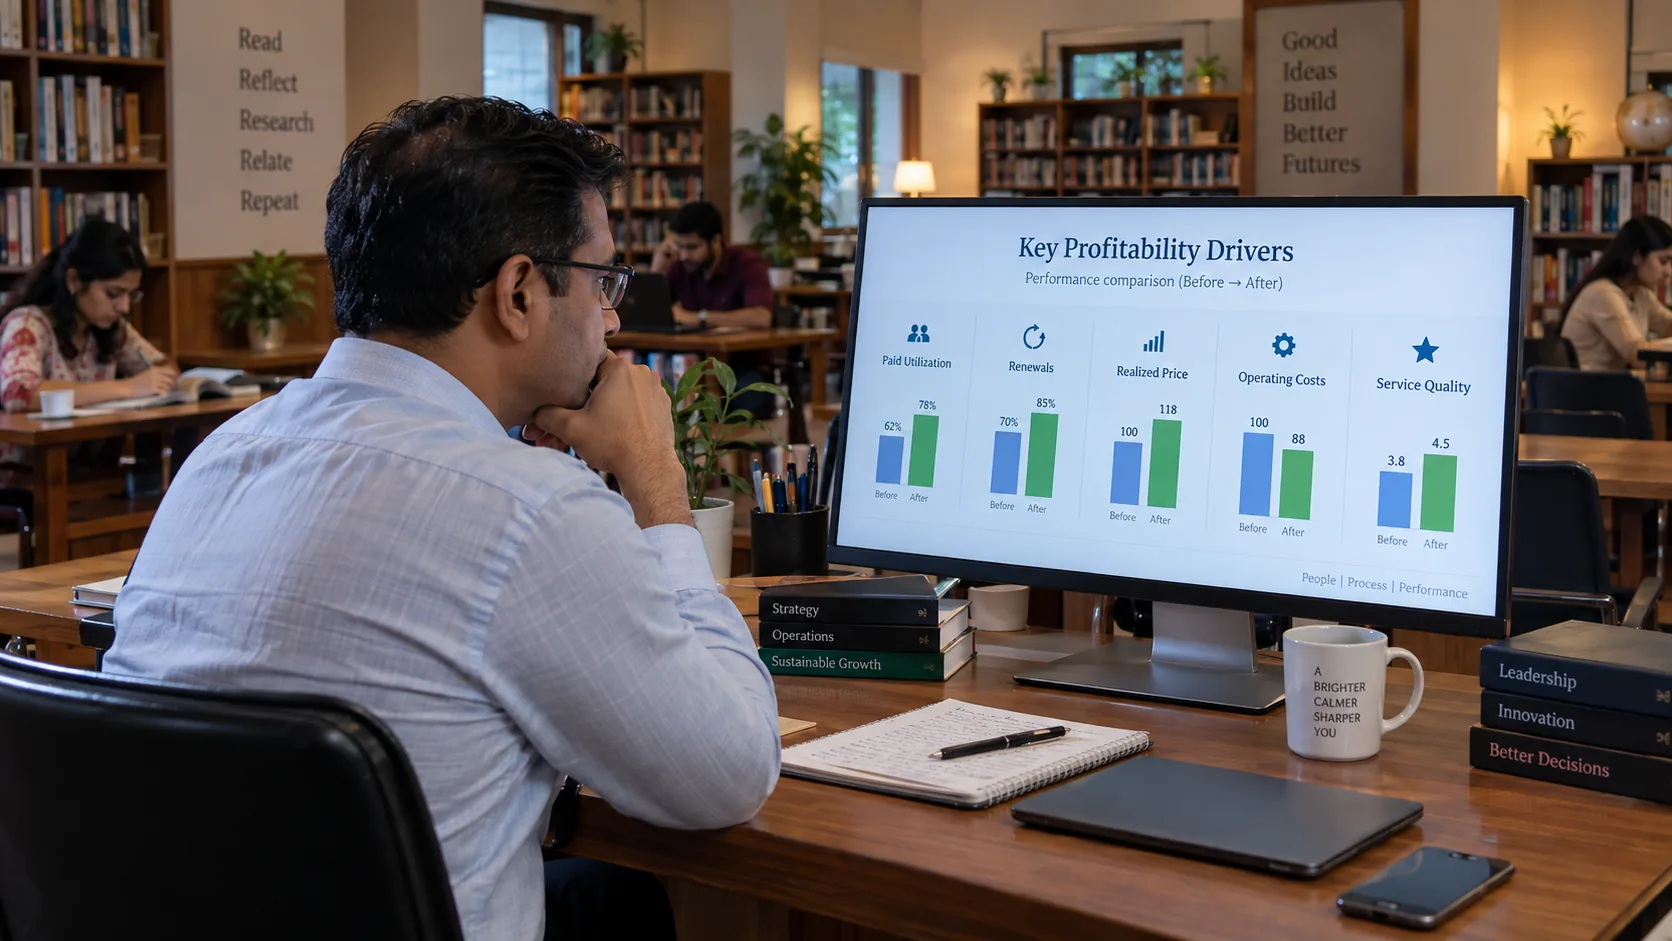
Costs, productivity and service quality
Review fixed, variable, mixed and step costs. A cost reduction is not an improvement if it creates more complaints, errors, maintenance issues, staff dependency or member churn. Productivity improvements should remove avoidable work while keeping ownership, permissions and exception handling clear.
Test price, shifts and promotions carefully
A higher price can raise contribution or reduce demand. An extra shift can use capacity or create step costs. A discount can create an incremental member or simply reduce the price paid by someone who would have joined anyway. Use scenarios and a baseline; do not present hypothetical outcomes as benchmarks.
Prioritize and measure
Rank ideas by expected effect, confidence, effort, risk, time to evidence and service-quality impact. Define the before period, after period, cohort, exclusions and source records. Measure profit, margin, realized price, utilization, renewals, collections, costs and service signals together.