Libix Logo· Library OS
  • FAQs
  • Features
  • Pricing
  • Solutions
  • About Us
  • Libix Learning
  • Libix Knowledge
  • Libix Learning/Financial planning/Study library discounts

    Financial planning · pricing discipline

    Should You Offer Discounts in Your Study Library?

    Decide when a discount has a real purpose, protect realized price and measure whether the offer created a worthwhile outcome.

    Indian study library owner reviewing a membership discount decision

    Quick answer

    Offer a discount only when it purchases a measurable business outcome

    Define the objective, establish a baseline, set eligibility, quantify the reduction, model economics, set guardrails, approve it, apply it transparently, measure the incremental outcome and then continue, modify or stop it.

    A discount is not automatically a strategy. It should not be a permanent substitute for pricing clarity or a reaction to every negotiation.

    Keep concepts separate

    Discount ≠ refund ≠ credit ≠ partial payment

    Discount decision framework

    A discount should purchase a measurable outcome

    Define objective→
    Establish baseline→
    Define eligibility→
    Model economics→
    Set guardrails→
    Approve→
    Apply transparently→
    Measure→
    Continue / modify / stop

    Discounts are neither universally good nor universally bad. Their value depends on purpose, economics, control and evidence.

    Discount type classifier

    Choose the business purpose before choosing the percentage

    Selected objective: Acquire incremental members

    Discount impact calculator

    Separate base price, discounted price and realized price

    Illustrative scenario only. It does not prove incrementality, determine tax treatment or decide whether a discount is eligible.

    Illustrative output

    1,620 realized per member

    ₹1,620

    Baseline cohort revenue ₹36,000

    Discounted cohort revenue ₹32,400

    Illustrative incremental contribution ₹3,600

    Measurement panel

    Do not confuse volume with success

    Base price

    ₹1,800

    Displayed or configured price before the offer.

    Discounted price

    ₹1,620

    Price after the defined reduction.

    Realized outcome

    Need evidence

    Compare with a defined baseline and legitimate incremental result.

    Staff authority matrix

    Control eligibility, negotiation and approval

    StaffExplain active offersNo free-form price change
    ManagerApprove configured exceptionReason and evidence required
    OwnerChange policy or guardrailReview economics and outcomes
    SystemApply eligibility ruleRecord source and effective dates

    Discount leakage and stacking

    Prevent the offer from becoming the price

    Leakage can come from expired offers, unclear eligibility, manual overrides, duplicate codes, stacking or discounts applied without a source. Record the offer, member eligibility, approval, dates and realized amount.

    A discount should be visible on the relevant financial document and remain distinguishable from a refund, credit, partial payment or payment reversal.

    Continue / modify / stop review

    Close the loop with evidence

    Continue: objective and incremental outcome supported
    Modify: outcome possible but control or economics need change
    Stop: no clear purpose, weak evidence or harmful economics

    Completed checks: 0/9.

    Start with the objective

    A discount might be intended to acquire a defined new-member segment, support a measurable renewal outcome, trade longer commitment for a different price, reward attributable referrals or apply an approved concession. If the reason is simply that a prospect asked, occupancy feels weak or a competitor changed price, define the actual business question before reducing the price.

    Define price, discount and realized price

    Base price is the configured or displayed amount before the offer. Discounted price is the amount after the defined reduction. Realized price is what the business actually earns under the relevant commercial and financial rules after legitimate discounts, concessions, partial periods, refunds, dues or other adjustments. These values should not be collapsed into one label.

    Model contribution, not just admissions

    A discount can increase volume while reducing contribution per member. Compare a defined baseline against the promotion cohort and consider variable costs, capacity, member quality, duration, renewal behaviour and collection quality. A higher count does not prove incrementality: some discounted members may have joined anyway.
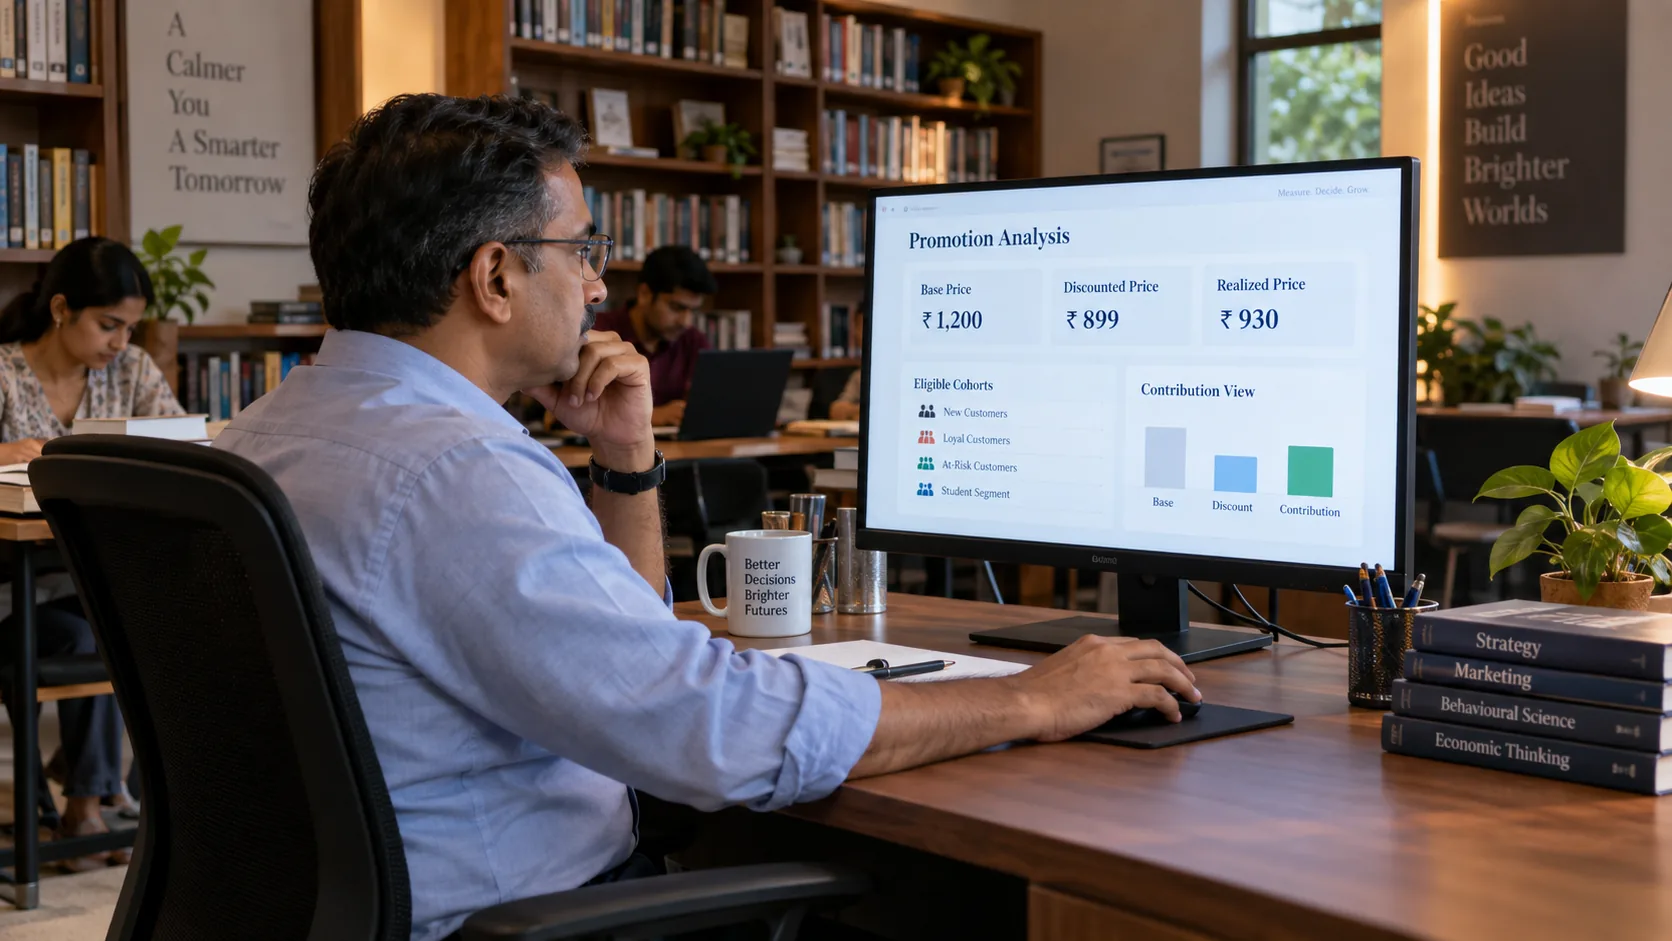
    Study library manager comparing base price discounted price and realized price

    Control eligibility, stacking and leakage

    An offer should have a start date, end date, eligibility rule, source, approval scope and document treatment. Decide whether offers can stack, which price is the basis for each reduction and how expired or duplicate codes are handled. Staff should be able to explain active offers without creating free-form exceptions. The discount should remain visible and distinguishable from a refund or payment correction.

    Use alternatives when a discount is the wrong tool

    Alternatives can include clearer plan packaging, better shift fit, improved service communication, a defined referral programme, a non-price benefit, a limited trial or operational improvements. A pricing reduction should not compensate for an unclear offer or a weak customer experience indefinitely.

    Review, modify or stop

    Review the promotion against the original objective and baseline. Examine realized price, contribution, incremental admissions or renewals, leakage, stacking, eligibility exceptions, capacity impact and member quality. Continue when evidence supports the purpose, modify when controls or economics need work, and stop when the offer has no clear or worthwhile outcome.

    Where Libix fits

    Make pricing decisions controlled and explainable

    Libix — Library OS is a study-library operations product from CodePex Technologies Private Limited. This guide presents a decision framework; current Libix discount, eligibility, approval, pricing and reporting capabilities must be verified before making a product claim.

    Review price changesReview margin contextUnderstand partial payments

    Discount SOP

    Before publishing or extending an offer

    □ Write objective
    □ Set baseline
    □ Define eligibility
    □ Model contribution
    □ Set dates and guardrails
    □ Assign approval
    □ Prevent stacking leakage
    □ Measure realized outcome
    □ Continue, modify or stop

    FAQs

    Study-library discount questions

    Should every study library offer discounts?

    No. Discounts are neither universally good nor bad. They should have a clear business purpose, controlled eligibility, defined economics and measurable outcomes.

    What is the difference between a discount and a refund?

    A discount changes the price or valid obligation before or during the commercial decision. A refund returns eligible money after collection. They are different financial events.

    Can discounts increase occupancy?

    Possibly, but a higher number of discounted members does not prove an incremental or profitable outcome. Compare against a defined baseline and contribution assumptions.

    Should staff negotiate discounts freely?

    Free-form negotiation creates leakage and weakens price credibility. Use defined offers, authority, eligibility, dates and approval paths where discounting is justified.

    When should a promotion stop?

    Stop or modify it when the purpose is not supported, economics are harmful, leakage is high, or the evidence does not show a worthwhile incremental outcome.

    Back to Libix LearningBrowse Libix Knowledge

    Claim your 6 months Free Trial

    Start with a free demo or get in touch with our team to learn more about Libix and how we can help your library succeed.

    Call Us - +91 91700 91269Email Us

    Libix is the simplest library management software for modern libraries in India. Built to help library owners focus on their members instead of spreadsheets.

    CIN : U93000UP2017PTC091269
    URN : UDYAM-UP-50-0143487
    Privacy Policy·Terms & Conditions·Refund Policy·Trial Policy·Disclaimer·

    Libix is a proud product of CodePex Technologies Private Limited.
    © 2026 Libix · All rights reserved.