
Financial Strategy · Software decision method
How to Calculate the ROI of Study Library Management Software
Build a decision case from your own baseline, relevant incremental cost, attributable benefit and evidence quality—not from an assumed uplift or a guaranteed payback.
Quick answer
Use this sequence: define the decision and horizon; document the current baseline; list only relevant incremental costs; identify measurable financial benefits; estimate the portion reasonably attributable to the software; remove overlaps; calculate net benefit and percentage ROI; then test conservative, base and upside assumptions. The core definitions are:
Net software benefit
Attributable financial benefits − relevant software costs
Software ROI
Net software benefit ÷ relevant software costs × 100
Do not credit the software for every improvement that happens after launch. If the denominator is ₹0, percentage ROI is not meaningful; report the benefit and zero-cost condition separately.
What ROI means—and what it does not
ROI is a decision metric, not a promise. It asks whether the financial value reasonably connected to a software decision exceeds the relevant cost of that decision. It is narrower than business profit and different from total cost of ownership, payback and break-even.
ROI
Compares attributable benefit with relevant cost. It is useful only when scope, timing and attribution are clear.
TCO
Describes the full ownership cost boundary, including costs that may not be used as an ROI denominator for a particular incremental decision.
Profit margin
Describes business profit relative to revenue. Software can affect costs or workflows without being the sole cause of margin movement.
Break-even and payback
Break-even asks when cumulative economics cross a threshold; payback estimates when upfront investment is recovered from stable recurring net benefit.
Start with the decision and horizon
Adopting a first system, replacing an existing system, renewing a contract and expanding deployment are different counterfactuals. Name which alternative is being compared. Then choose a horizon that matches the decision—for example, a first-year adoption case or a renewal period—and use that same horizon for recurring costs and benefits.
| Decision | Useful comparison | Common mistake |
|---|---|---|
| Adopt | Current manual or spreadsheet process vs proposed system | Using a vendor promise as the baseline |
| Replace | Existing system vs proposed change | Counting all new cost but ignoring retired cost |
| Renew | Renewal cost vs credible continuation value | Treating historic setup cost as new cost |
| Expand | Incremental branches, seats or modules | Crediting the expansion with benefits from the whole business |
Make the baseline observable
Record the current process before estimating impact. A useful baseline may include member renewals, seat occupancy, collection ageing, correction effort, enquiry handling time, reporting effort, active staff hours and known leakage. Define the period, source, unit, owner and evidence quality. A baseline is not “the business feels slow”; it is a measurable starting point with boundaries.
Count relevant software costs
Relevant cost is the incremental cost caused by the decision, on the same basis as the benefit. Separate recurring subscription or licence from implementation, migration, training, hosting, support, required messaging or payment services, infrastructure, internal implementation time and other material cost. Mark each line as one-time or recurring and distinguish required from optional.
For replacement or expansion, consider both new cost and credible retired cost. Do not hide tax, usage, migration or internal effort simply because a quotation labels them separately.
Trace benefits through an evidence chain
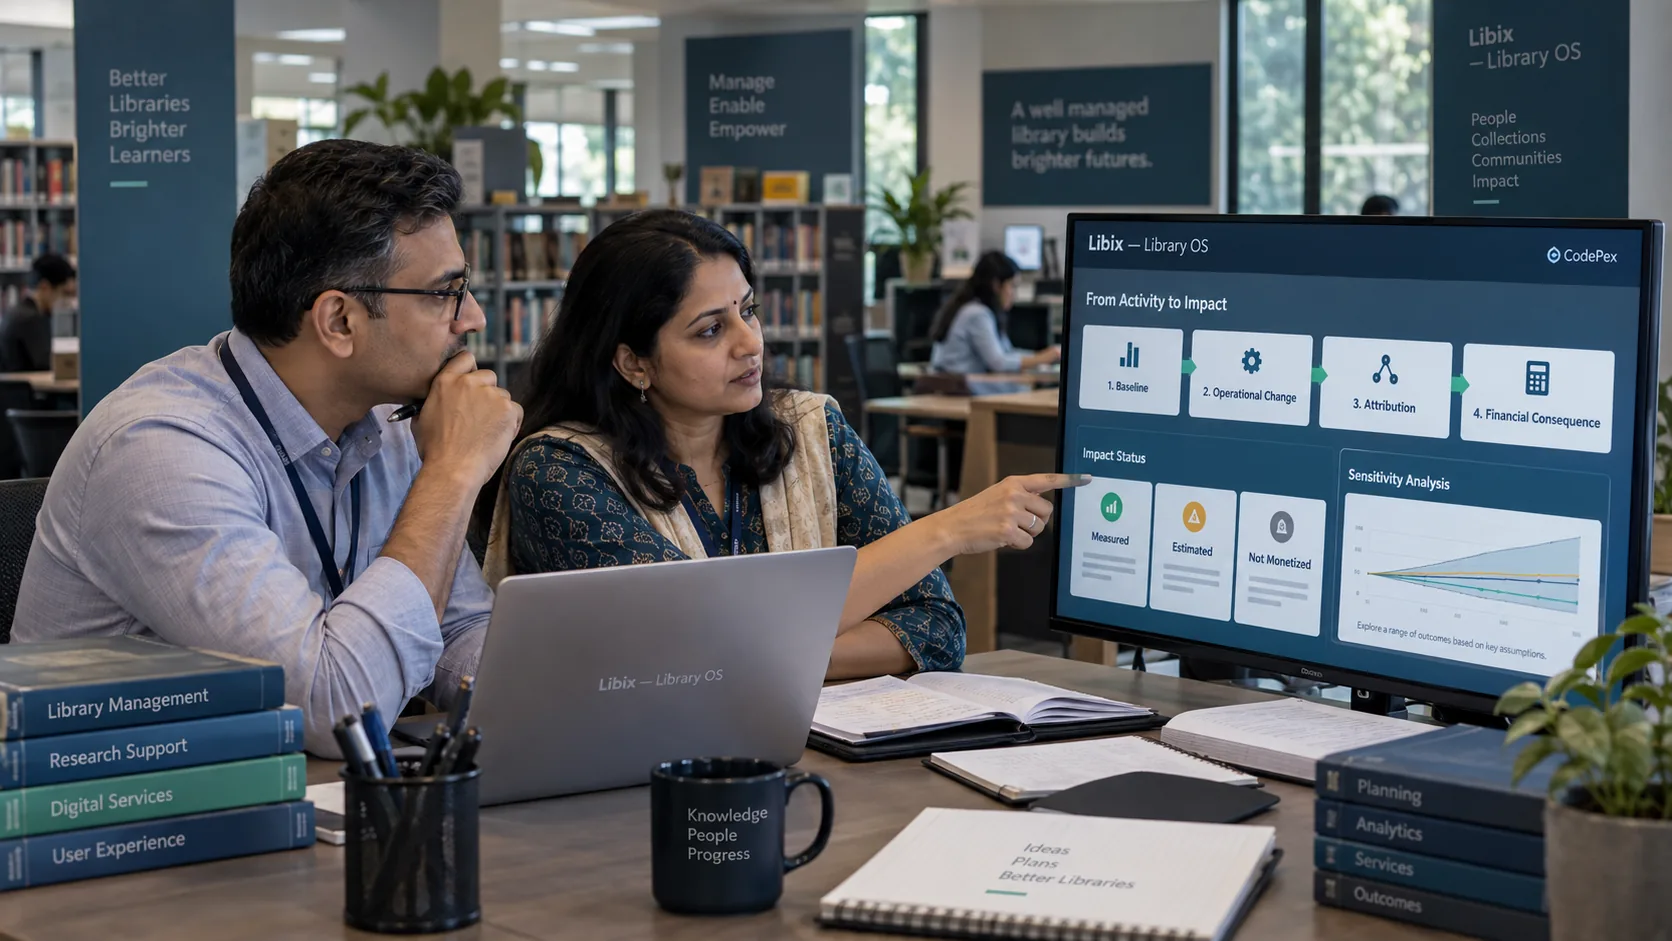
A capability is not yet a benefit. Connect the proposed capability to a workflow change, an observable operational outcome and then a financial consequence. For example: a reliable renewal reminder workflow → fewer missed renewal follow-ups → measured change in renewal completion → attributable contribution after considering margin and other causes.
Capability
Workflow change
Measured outcome
Financial consequence
Possible areas include renewals, occupancy, collections, leakage, correction work and administration. None is automatically a software benefit. Each needs a baseline, post-change observation and a reasoned attribution share.
Revenue needs contribution logic
Incremental revenue is not the same as incremental benefit. If a change in membership or renewals is measured, use incremental contribution where appropriate: incremental revenue × contribution margin. Consider discounts, capacity, variable service cost, refunds, bad debt and whether the same members would have arrived without the system.
For collections, distinguish faster cash timing from new revenue. For occupancy, distinguish additional paid use from a percentage shown on a dashboard. For leakage, compare validated baseline loss with validated post-change loss and include only the attributable reduction.
Treat time saved carefully
Hours saved in admissions, attendance, collections, reporting or correction work can matter without being cash. To monetize them, multiply attributable hours saved by an owner-defined or evidence-based value per hour, then confirm what actually changes: paid staffing, owner capacity, additional service, avoided overtime or a credible opportunity cost. Do not silently turn every saved minute into revenue.
Hours saved
Record separately and explain the evidence.
Value per hour
Record separately and explain the evidence.
Economic consequence
Record separately and explain the evidence.
Use attribution and prevent double counting
Attribution is the portion of a financial movement reasonably connected to the software decision. It should be supported by a before/after comparison, a controlled rollout, a matched branch, a workflow log, a validated exception record or another explicit method. Keep revenue, renewals, occupancy, collections, leakage and time categories distinct enough to avoid counting one event twice.
| Evidence strength | Use in a case |
|---|---|
| Measured and linked | Strongest basis; preserve source, period and method. |
| Observed with confounders | Use a conservative attribution share and explain alternatives. |
| Owner estimate | Useful for scenario planning, not proof of realized benefit. |
| Vendor claim only | Do not treat as realized financial benefit. |
Formulas, payback and the zero-cost edge case
Use the same currency, period and scope throughout. Net software benefit equals attributable financial benefits minus relevant software costs. Percentage ROI divides that net benefit by relevant software costs and multiplies by 100. Payback is initial or upfront relevant investment divided by recurring net benefit per period, and is valid only when recurring net benefit is positive and sufficiently stable.
No positive recurring benefit
Do not report a positive payback period when recurring net benefit is zero or negative. Show that payback is not reached under the inputs.
Zero relevant cost
Percentage ROI is not meaningful because the denominator is ₹0. Report benefit and cost separately.
Same horizon
Do not compare one month of cost with a year of benefit, or a one-time benefit with a recurring cost without explaining timing.
Use conservative, base and upside cases
Scenarios are not permission to invent a range. Change assumptions you can explain: attribution percentage, realized benefit, implementation cost, adoption speed, capacity constraints or support cost. The conservative case should include known friction and should not be presented as a guaranteed floor. A sensitivity table can reveal which assumption actually drives the decision.
Conservative
Lower attributable benefit, higher relevant cost or slower adoption
Base
Best current estimate with documented evidence and open assumptions
Upside
A possible result if the specified enabling conditions occur
Worked examples: label assumptions clearly
Imagine an owner comparing a proposed system over 12 months. The case includes ₹12,000 of recurring cost, ₹20,000 of one-time implementation and ₹10,000 of validated financial benefit with 50% attribution. The attributable benefit is ₹5,000, relevant cost is ₹32,000 and net software benefit is −₹27,000. The result is a negative ROI under those assumptions—not a reason to adjust attribution until the answer looks attractive.
A separate illustrative case might include ₹40,000 of attributable contribution and ₹32,000 of relevant cost, producing ₹8,000 net benefit and 25% ROI. These numbers are examples only; they are not market data, a forecast or a Libix claim.
Review forecast versus actual after implementation
After the chosen period, compare forecast with actual using the same definitions. Preserve baseline, post-change data, implementation date, adoption level, exceptions, costs paid, benefits realized, attribution rationale and non-financial outcomes. Record why results differed instead of rewriting the original case.
Try the transparent ROI calculator
Enter your own values. Blank cost and benefit fields are treated as zero for arithmetic, not as evidence. Keep unmonetized time and non-financial value separate, and review warnings before using an output in a decision.
Client-side ROI calculator
Build a transparent software business case
All values are owner-entered. There are no default uplift percentages, attribution assumptions, labour rates or Libix-specific benefits. Empty values are treated as zero for calculation, not as evidence that the category is zero.
Financial benefits
If time is not monetized, it remains an operational benefit and is not included in financial ROI.
Non-financial benefits
Relevant cost · 12 months
₹0
Attributable financial benefit
₹0
Net software benefit
₹0
ROI over horizon
Not meaningful
Percentage ROI is not meaningful because relevant cost is ₹0.
Decision: adopt. Baseline: manual registers. Monetized time included: no (₹0). Payback: not reached or not applicable under current inputs. Non-financial benefits remain separate.
Educational decision support only. No backend, persistence, PII, financial guarantee, default ROI, scenario range or product recommendation is used.
Where Libix fits
Verify the product case separately
Libix can be evaluated against the workflows, controls, evidence and commercial boundary that matter to your study library. This guide does not claim a particular uplift, price or ROI. Verify current capabilities, support, implementation scope, data portability and commercial terms from authoritative product material, then use your own baseline and attribution evidence.
ROI decision checklist
Frequently asked questions
What is the ROI formula for study library management software?
Software ROI equals attributable financial benefits minus relevant software costs, divided by relevant software costs, multiplied by 100. Benefits and costs must use the same decision horizon.
Which costs belong in a software ROI calculation?
Include relevant incremental recurring and one-time costs such as licence, implementation, migration, training, hosting, support, required services, infrastructure and other costs caused by the decision.
Can extra renewals or occupancy be counted as software benefit?
Only when a defensible baseline, measured change and attribution rationale support the claim. Software should not receive credit for changes that have other plausible causes.
How should time saved be treated?
Time saved is an operational benefit. Include it in financial ROI only when the hours can be monetized using an owner-defined or evidence-based value and the economic consequence is real rather than merely theoretical.
What happens when relevant software cost is zero?
Percentage ROI is not meaningful because the denominator is ₹0. Report the attributable benefit and zero-cost condition separately; do not describe the result as infinite ROI.
Does positive ROI mean the software is the right decision?
Not by itself. Check evidence quality, cash timing, risk, non-financial value, operational fit, alternatives and whether the result survives conservative assumptions.
Does Libix guarantee a particular ROI?
No. Libix-specific capabilities, commercial terms and any business outcome must be verified from current authoritative documentation and the owner’s own evidence.